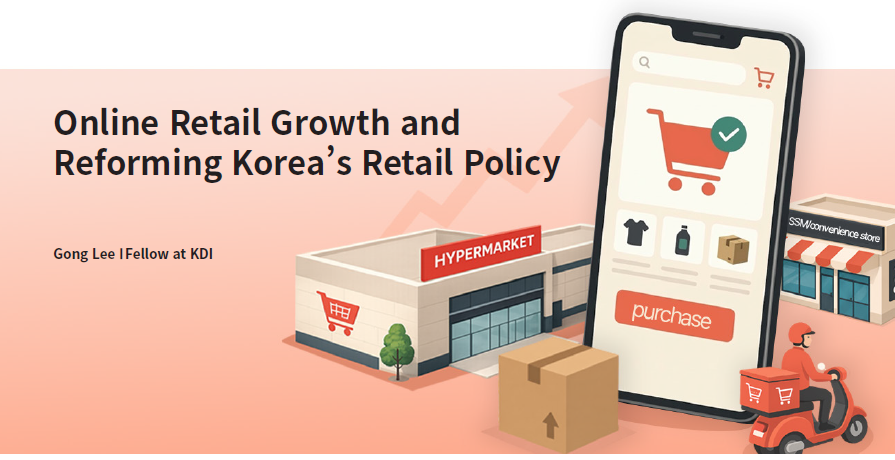
The analysis shows that a 1% rise in a neighborhood's per capita online spending is associated with a 0.186% increase in its total offline sales. That runs against the conventional view of online and offline channels as competing substitutes. The increase came mainly from more stores (+0.152%) and more customers per store (+0.045%), not from larger purchases or more frequent shopping trips, which showed no significant change. The report suggests that online shopping may stimulate latent consumer demand, and that offline retailers may be responding by opening stores closer to consumers. In short, online growth does not simply reshuffle existing demand.
?? But hypermarkets lost ground while neighborhood retailers gained
The overall figure hides a split. For hypermarkets (analyzed at the city/county/district level), a 1% rise in local per capita online spending is associated with a 0.264% decline in sales, pointing to direct competition with online channels. For corporate supermarkets (SSMs), convenience stores, and other specialized retailers such as butcher shops and household goods stores, the same rise is associated with sales growth of 0.221%, 0.324%, and 0.356%, respectively. These formats are anchored in neighborhood commercial districts, and their proximity lets them compete for demand that online channels serve less well. Convenience stores nationwide increased by about 27.6% between January 2020 and December 2024. Against this backdrop, the report describes Homeplus's crisis as appearing structural in nature, rooted in broader shifts in the retail landscape rather than in one company's management alone.
?? The law still reflects the retail market of 2012
According to the Ministry of Trade, Industry and Energy's data on major retailers, online retail sales reached about 97.74 trillion won in 2024, more than double the 2018 level of 48.05 trillion won. Online's share of total sales passed 50% in 2023 and reached 60% by March 2026. Yet the Distribution Industry Development Act, enacted in 1997 and amended in 2012, still centers on large offline stores through operating-hour limits, mandatory closing days, and controls on new store openings. Online platforms competing for the same consumers face no comparable requirements, and the report finds that this asymmetry undermines both fairness and efficiency across the sector. Since hypermarket sales fall as online spending grows, it is also increasingly doubtful that regulating hypermarkets remains an effective way to protect traditional markets.
?? Policy Implications
1?? Ensure regulatory parity between online and offline channels, so the burden does not fall on a single retail format
2?? Help traditional markets and other neighborhood retailers expand local consumer access, offer what online channels cannot easily replace (local specialties, ready-to-eat food, community-based services), and go digital through O2O (online-to-offline) integration and data-driven marketing
3?? Continuously monitor how advances in online logistics, such as Rocket Delivery or any future C-commerce (China-based platforms such as Temu and AliExpress) delivery networks, affect offline retail, and reflect the findings promptly in policy
4?? Strengthen the Korea Fair Trade Commission's monitoring of online platforms' abuse of superior bargaining position, such as unreasonable commission increases or favoring their own offerings, to keep competition fair